The Big Picture
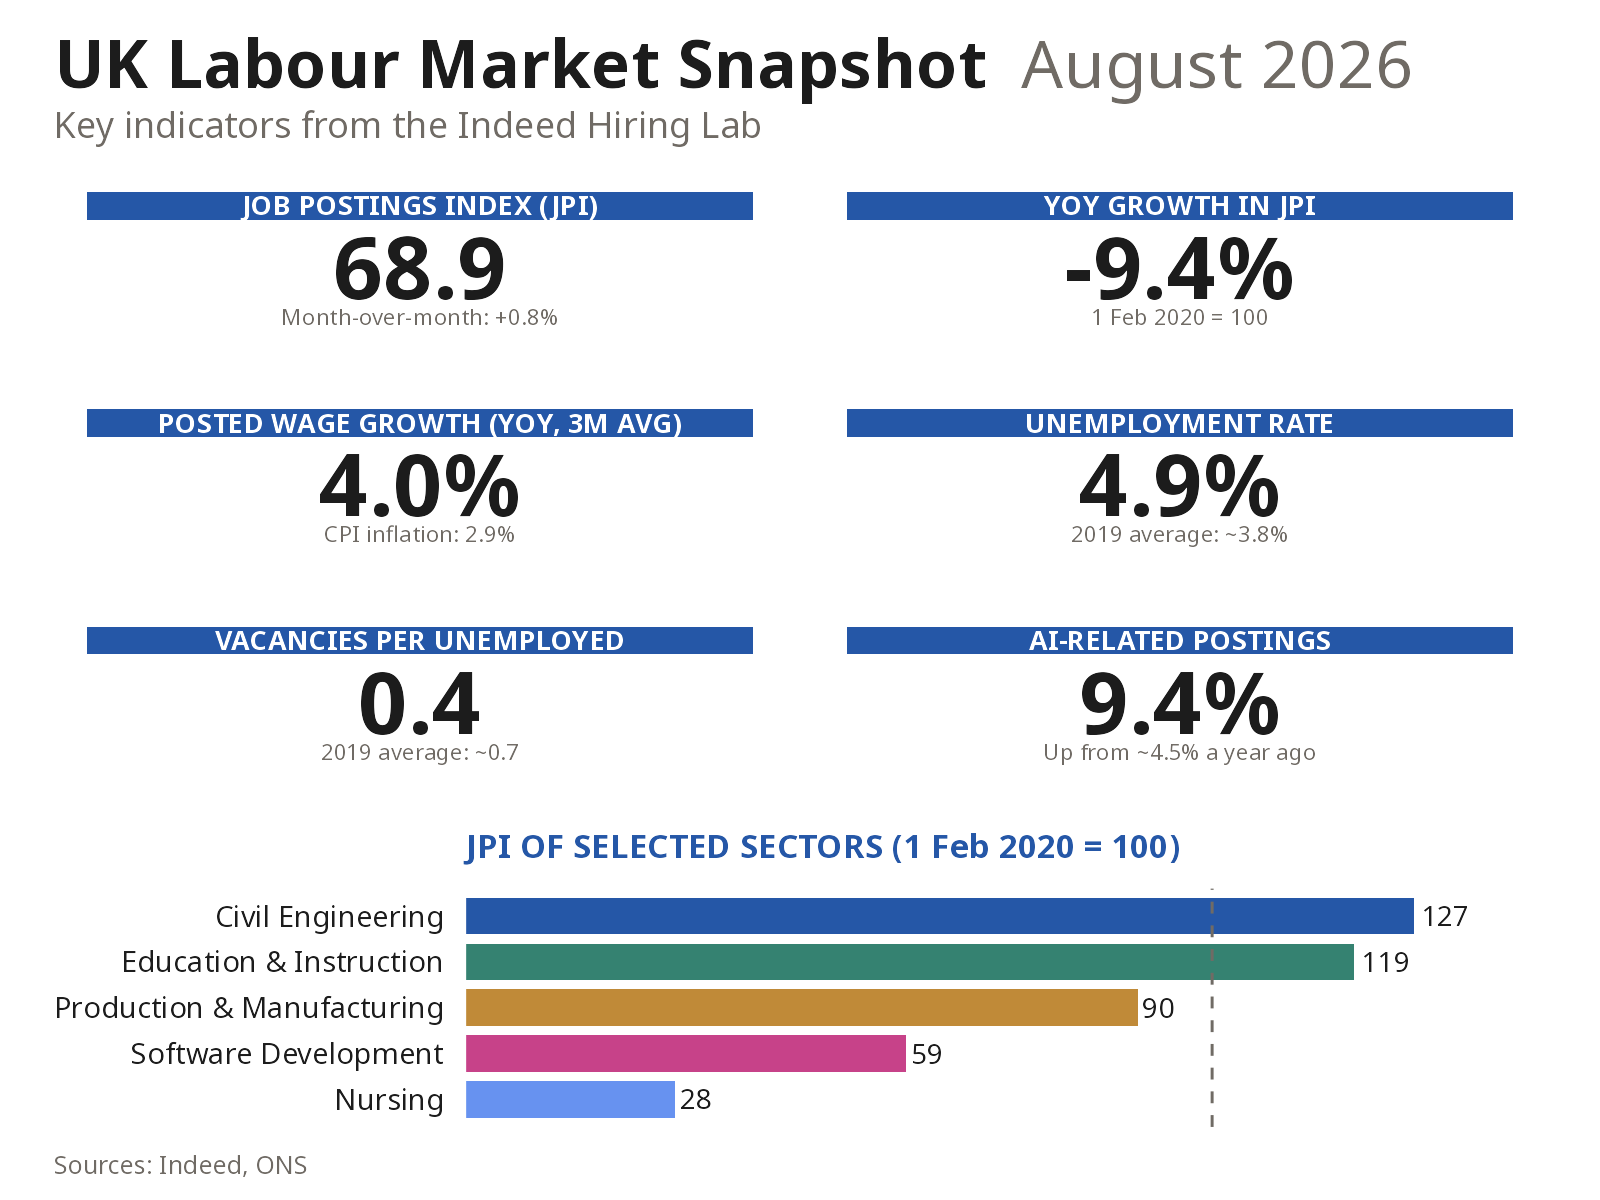
Overall hiring demand has remained steady since the start of June, following a period of softening. UK job postings on Indeed increased slightly in the month to 14 August, recording 0.8% growth. But postings still sit 31% below early-2020 levels, with employer confidence remaining low. That’s despite the working-age population having grown by 4.7% over the period. The low-hire, low-fire labour market pattern shows few signs of changing, with redundancies remaining modest while hiring appetite remains weak as businesses navigate cost pressures.
Job Postings
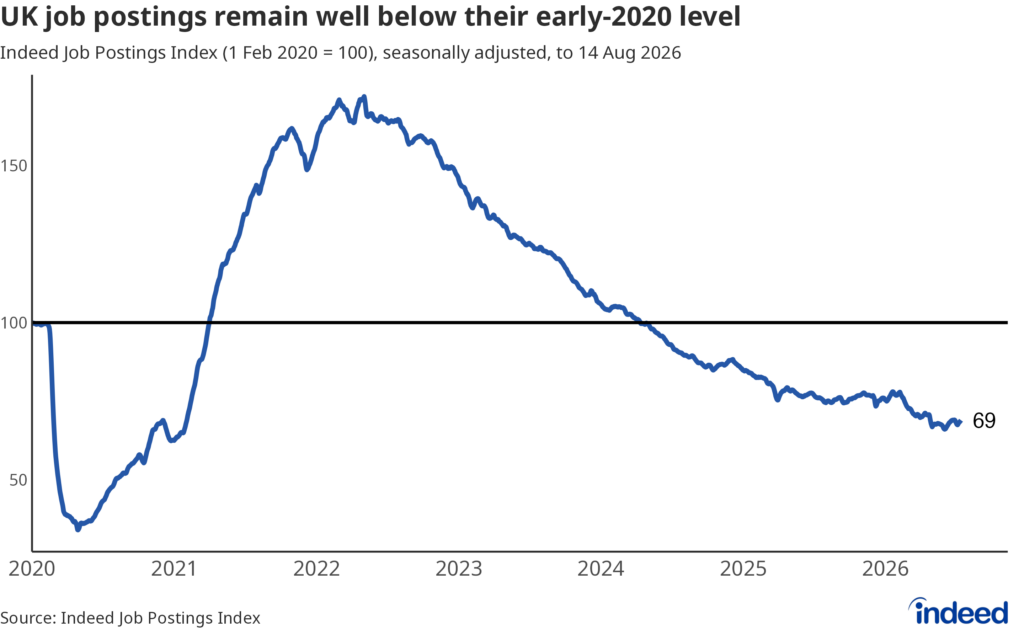
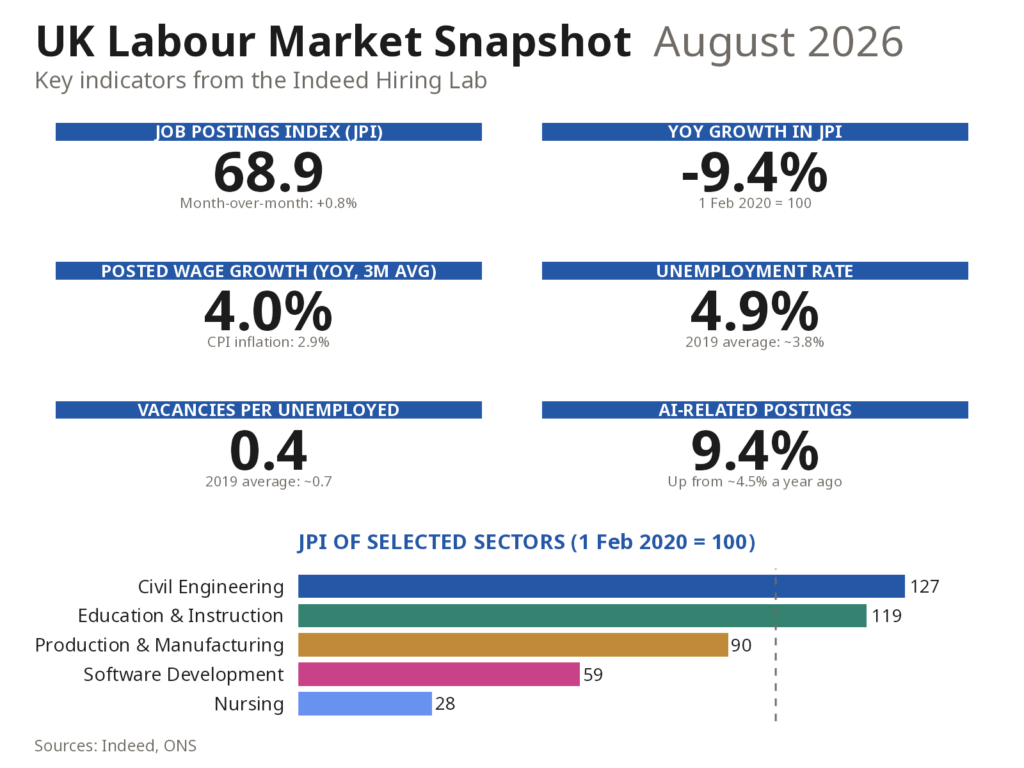
Where we are: The Indeed Job Posting Index (JPI) weakened from March through May, but has stabilised in recent months. Even so, it remains well below pre-pandemic levels, standing at 69 as of 14 August. New postings (job postings on Indeed for 7 days or fewer) show a moderately firmer trend, running at a range of around 85 in recent weeks (15% below their pre-pandemic baseline).
Direction of travel: Labour demand has been broadly stable since the start of June. While monthly growth in the JPI has turned slightly positive at 0.8%, the year-over-year change still shows a sharp -9.4% decline.
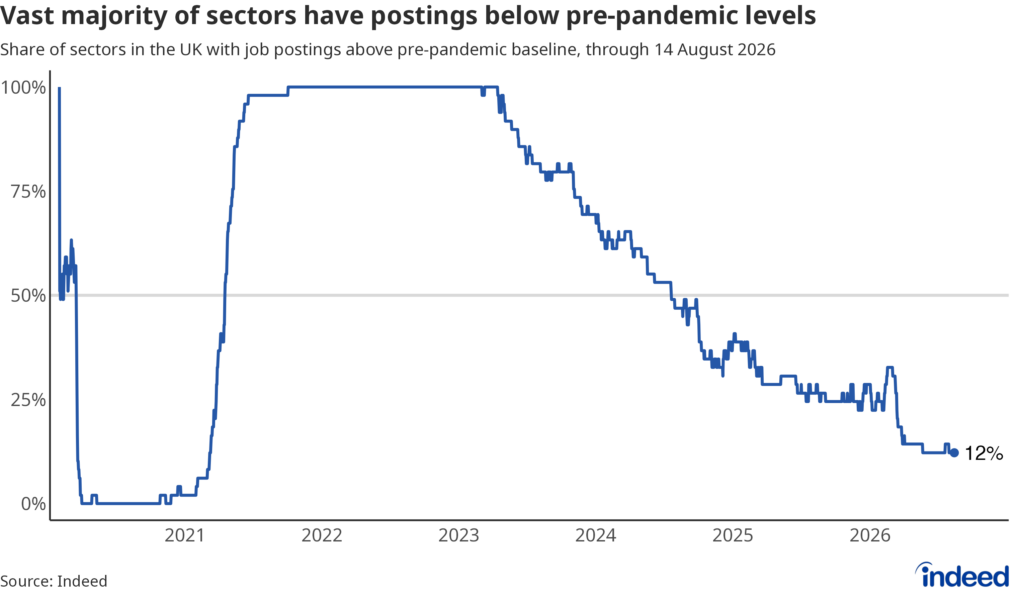
Sector split: The vast majority of sectors tracked sit below their pre-pandemic levels in terms of overall postings on Indeed. Only a handful of categories, including Civil Engineering and Education & Instruction, continue to have postings higher than the baseline. Meanwhile, Nursing and Software Development roles remain far below baseline.
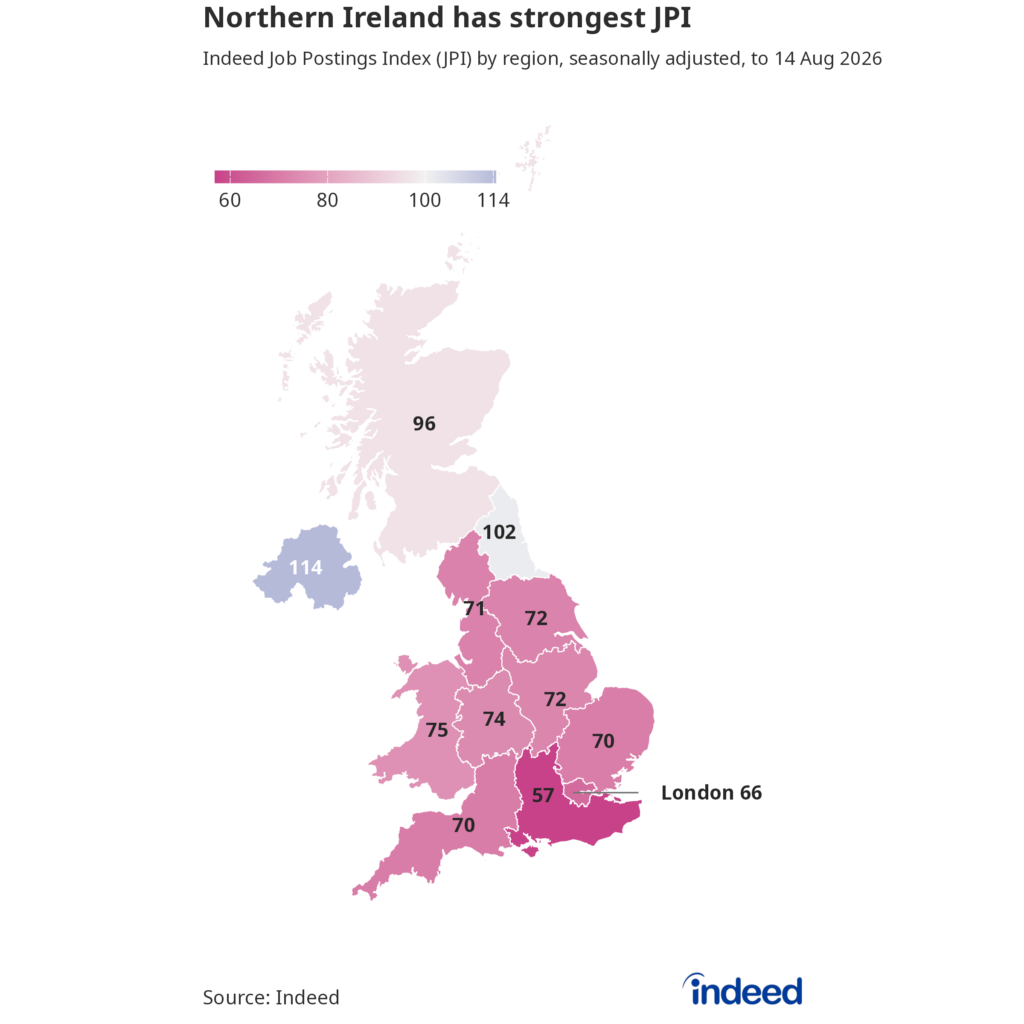
Regional variation: Northern Ireland (115) has the highest JPI, having seen its index rise by 5 points over the past year. The North East (102) is the only other region with job postings above baseline. The South East (57) and London (66) have the lowest JPI levels.
Middlesbrough is the city with the highest JPI (114), followed by Belfast and Sunderland (both 106). Reading (47), Brighton and Slough (both 52) have the lowest JPI. Every city or large town has seen a decline in its JPI over the past year, with the exception of Plymouth, which saw a marginal increase.
Wages
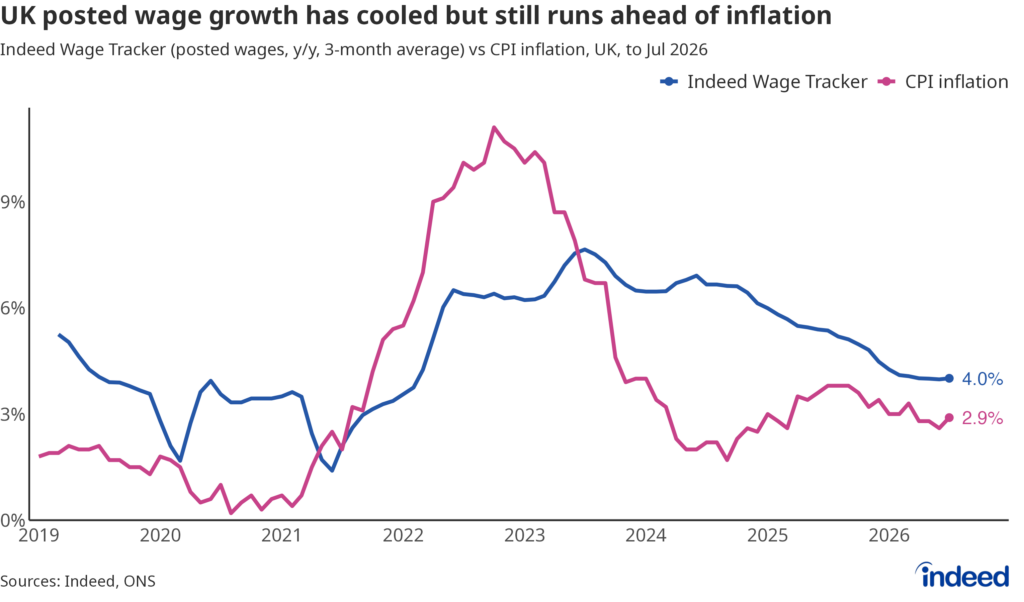
Headline: Posted wages rose 4.0% over the year ending July 2026, matching their annual growth rate from the prior three months. Advertised wages have been growing more quickly than prices since mid-2023. However, the gap has narrowed considerably as wage growth has gradually cooled and inflation has crept higher.
The Labour Market Balance
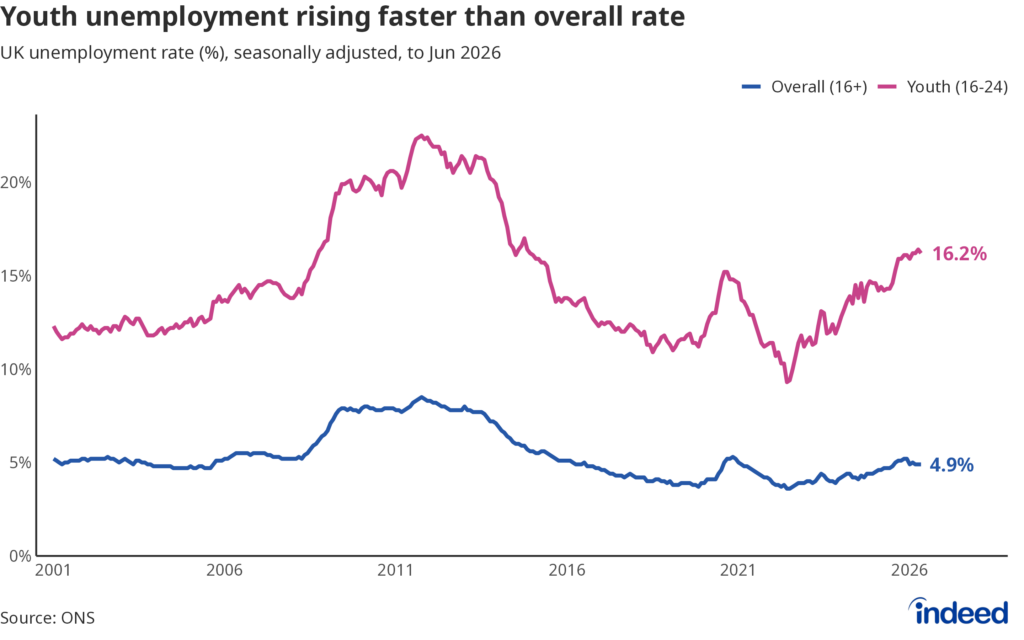
Unemployment: The unemployment rate remains relatively low, sitting at 4.9% in the three months to June – up from the mid-2022 low of just 3.6%, but broadly stable. However, the picture is more concerning for young workers. The rate of youth unemployment (16-24s) has been climbing steadily over the past four years and now stands at 16.2%, close to a 12-year peak and up sharply from 9.3% in mid-2022. Meanwhile, the vacancy-to-unemployment ratio held at 0.4 in June, indicating less than one available job vacancy for every two unemployed workers.
Job switching and redundancies: Rates of job-to-job switching remain close to historic averages, running at 2.3% in the second quarter of 2026. Meanwhile, redundancy notifications remain low. Rather than existing workers, it’s prospective new entrants to the labour market, such as recent graduates and other entry-level jobseekers, who are bearing the brunt of persistent weakness in hiring demand.
What We’re Watching
- AI adoption: The number of postings writing “AI” into job titles has risen sharply in the UK and other countries – almost tripling in the UK since 2022. AI in job titles is now more prevalent outside tech than in tech. The share of job postings in the UK that mention AI in the description continues to rise rapidly, now at 9.4% of all postings.
- Monetary policy: The Bank of England left interest rates on hold at its July meeting, with its Monetary Policy Committee voting 6-3 in favour of leaving rates unchanged. While the energy shock continues to put upward pressure on inflation, the weakness of the labour market suggests a lesser risk of upward price pressures becoming entrenched. That’s because workers have less bargaining power to push for compensating wage increases than they did during the 2022 energy shock, when the labour market was at its tightest. Events in the Middle East remain volatile and the Bank has signalled it may need to raise rates in the event of an escalation, but for now investors have been scaling back their bets on any rate increases for the remainder of this year.
The European chartbook with additional country coverage, sector and wage detail is available [here].
Methodology
Data on seasonally adjusted Indeed job postings are an index of the number of job postings on a given day, using a seven-day trailing average. February 1, 2020, is our pre-pandemic baseline, so the index is set to 100 on that day.
Data on wage growth are the average year-on-year percentage changes in wages and salaries advertised in job postings on Indeed, controlling for job titles.
Data on AI-related postings are the share of AI (and generative AI) job postings, as a percentage of overall job postings, using a seven-day trailing average. We calculate the aggregate share of job postings in a specific location that included keywords associated specifically with: AI (e.g., “Machine Learning,” “Data Science,” and “Artificial Intelligence”) and Generative AI (e.g., “Generative AI,” “Large Language Models,” and “Chat GPT”).