Key Points:
- Pay is losing ground to inflation. With both advertised wages and employment cost index falling below inflation, the typical raise hasn’t kept up with the rising cost of everyday goods. And workers feel it, rating their pay and benefits at the lowest level since 2017.
- The pressure has expanded to include benefits, led by health insurance. Health insurance remains the benefit workers value most, but employer costs are up and worker satisfaction with coverage is at a multi-year low.
- In 2027, focus on total compensation, not just the paycheck. The edge may go to employers who manage and advertise their benefits, including those valued by workers of different ages and experience levels.
In 2026, paychecks are losing ground to inflation – and rising benefit costs are squeezing what’s left. There are few signs the pressures will ease heading into 2027, likely forcing changes in how workers weigh a job offer and how employers think about recruitment and retention as employment costs keep rising.
Pay is losing ground
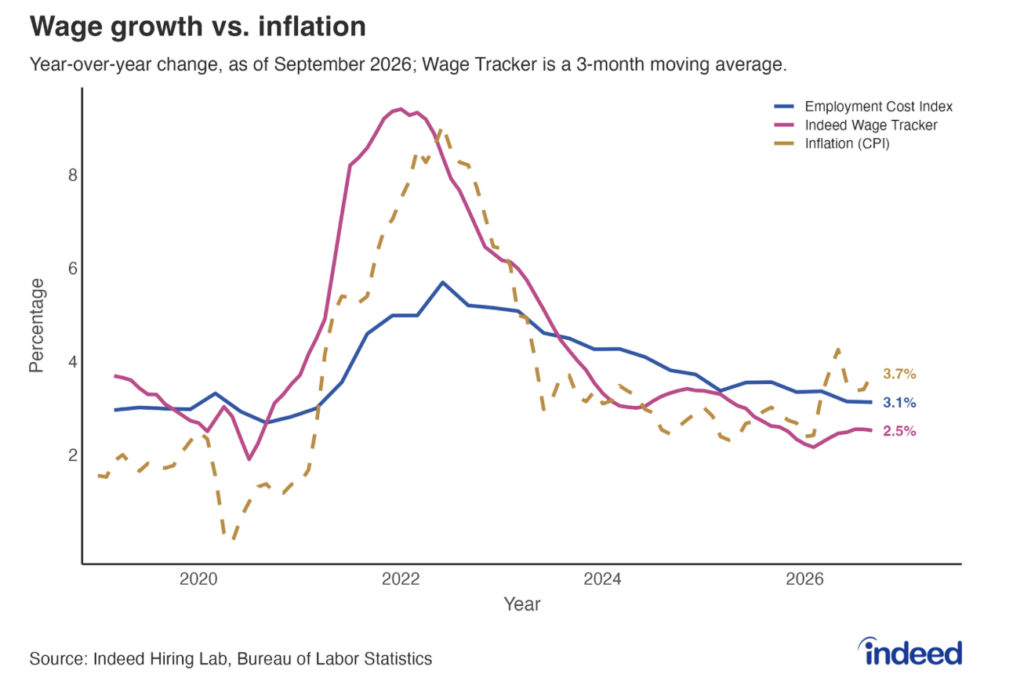
Wage growth has slowed and slipped below inflation. Advertised pay as measured by the Indeed Wage Tracker was up 2.5% year over year as of September 1, 2026, down from a peak of 9.5% reached in 2022. The Bureau of Labor Statistics’ Employment Cost Index (ECI), a measure of the change in employers’ labor costs over time, rose 3.1% year-over-year for private-sector wages and salaries in the third quarter of 2026. Meanwhile, annual growth in the headline Consumer Price Index, the main measure of inflation, exceeded both – clocking in at 3.7% in September.
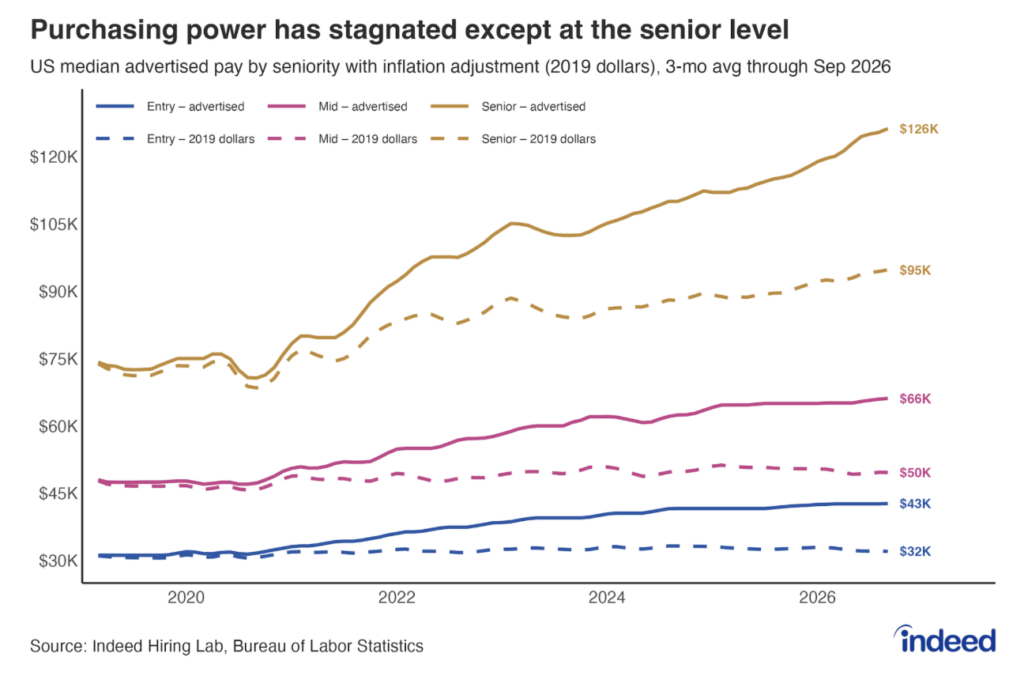
The wage gains that exist are concentrated at the top. Median advertised pay for senior roles has grown faster than entry- and mid-level roles, climbing from roughly $74,000 in 2019 to roughly $126,000 in 2026, or about 69%, with growth accelerating after 2022. Entry-level roles ($31,000 to $43,000, about 37%) and mid-level roles ($48,000 to $66,000, about 37%) grew more modestly, and the gap between mid-level and senior pay is large and widening. But few workers earn near the senior level. According to the Census Bureau, the typical full-time US worker earned about $65,000 in 2025.
Inflation erodes purchasing power. Prices have climbed about 33% since 2019, meaning that a basket of goods that cost $100 then costs about $133 today. Put another way, a dollar today is equivalent to 75 cents in 2019. For mid- and entry-level roles, today’s $66,000 buys about what $50,000 did, and $43,000 buys about what $32,000 did, respectively – meaning real wages for these groups have barely budged. But the median $125,000 salary now advertised for senior roles buys about what $94,000 did in 2019. This represents a considerable increase in real wages for senior level employees.
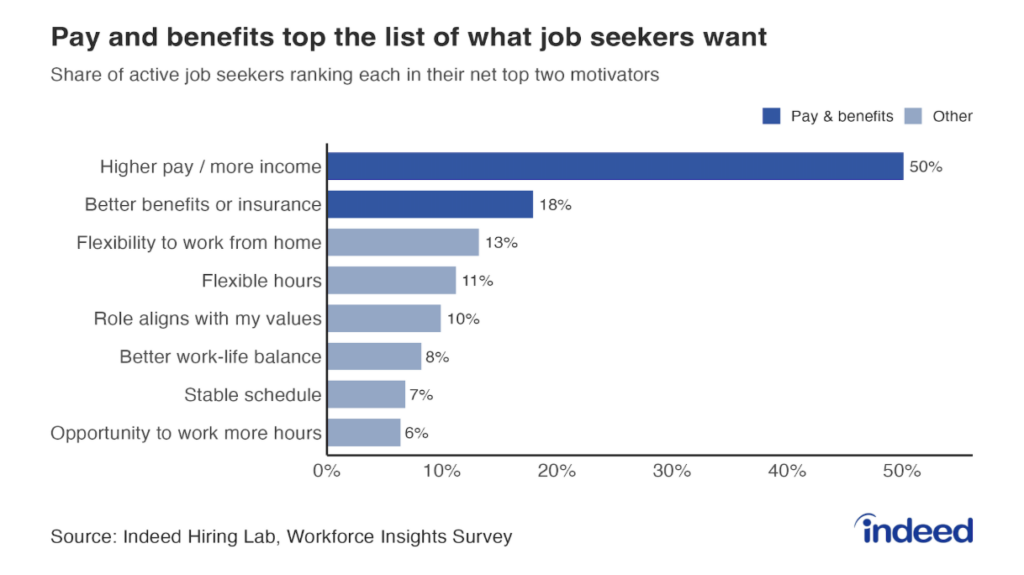
Against this backdrop, the 2026 Indeed Hiring Lab Workforce Insights Survey (WIS) shows that higher pay is the top motivator for job seekers, with half (50%) ranking it among their net top two reasons for searching. But pay isn’t the only factor, and better insurance is also a strong draw, cited by 18% of job seekers as a main motivator. Close behind were flexible hours, a role that fits their values, and better work/life balance.
Employers’ costs are rising, too…
But while values and schedule flexibility can often be relatively inexpensive benefits for employers to offer, providing other benefits can be quite costly – and is only getting more so.
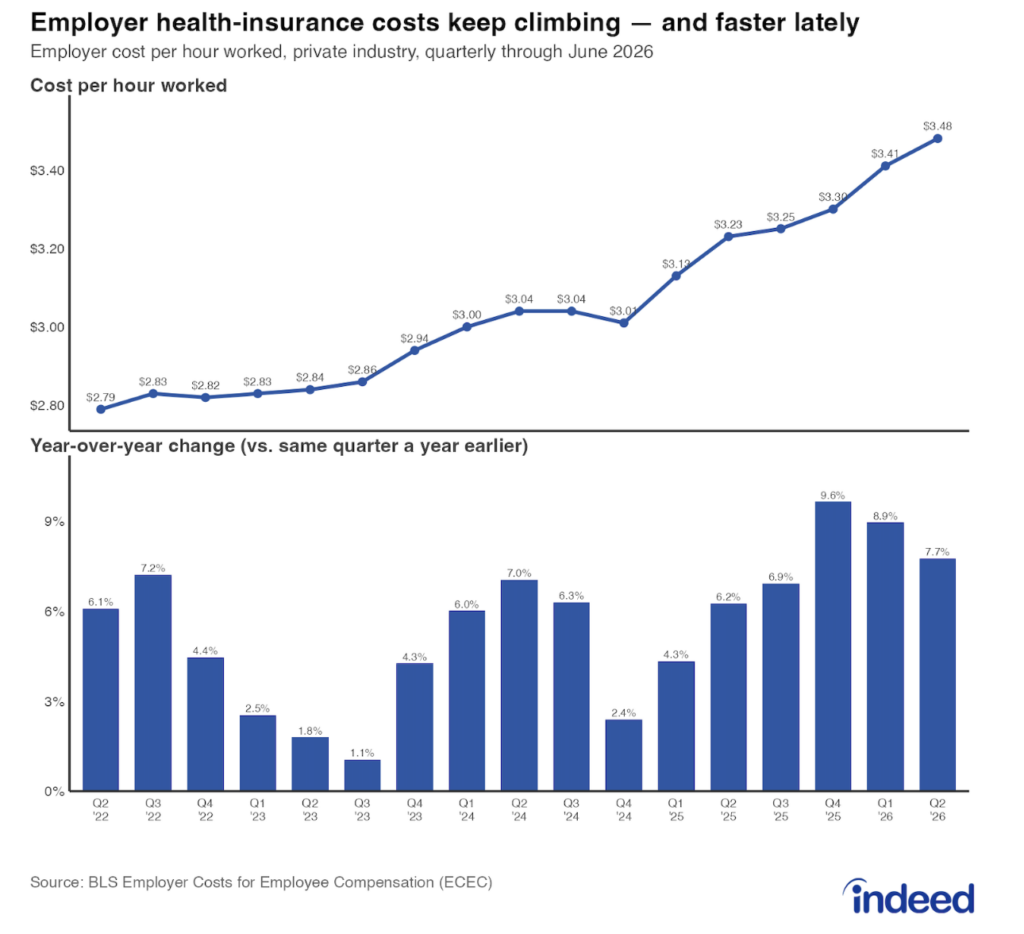
Health insurance is a prime example, as workers consistently ranked it one of the most important benefits. More than a third (34.7%) of workers said it was their most-valued benefit. And the cost of offering health insurance has been rising rapidly, particularly in the last year. According to the US Bureau of Labor Statistics’ June 2026 Employer Costs for Employee Compensation (ECEC), private-sector employers paid 25% more for health insurance benefits in 2026 than they did in 2022. After a brief plateau in 2024, the increases accelerated every quarter, running 7%-10% year-over-year for the past four quarters.
…and workers aren’t happy about the impact
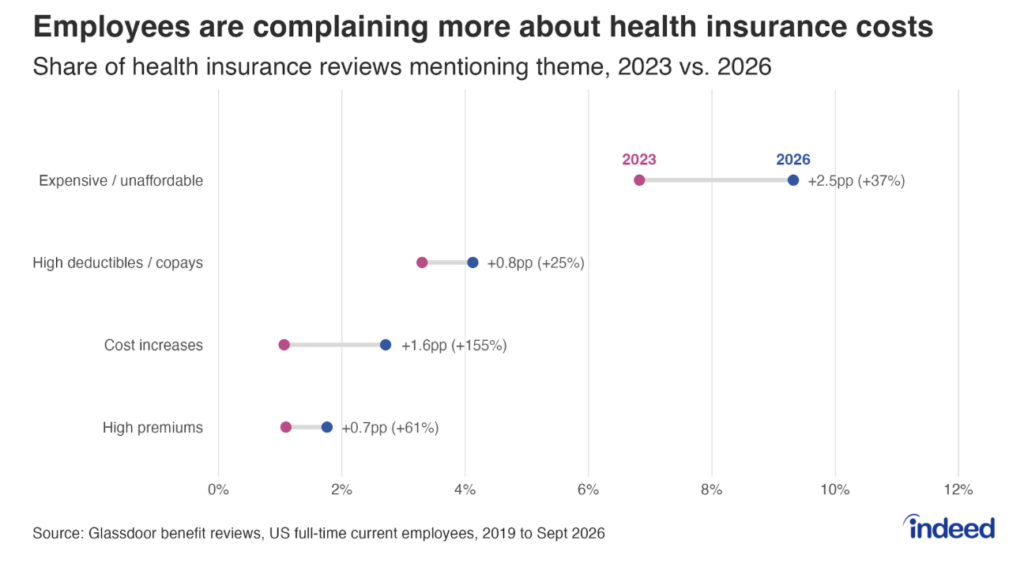
The rapidly rising costs of popular benefits like health insurance may leave employers with less room to raise baseline pay at exactly the time more workers need it to keep pace with rising inflation. Adding to the challenge to workers’ finances, employers may choose to mitigate their own rising costs by contributing less to premiums and asking their workers to shoulder more of the burden, and/or by switching to lower-quality plans. Workers are increasingly skeptical of these trade-offs, and their dissatisfaction is showing up in Glassdoor reviews.
Compared to 2023, employees are substantially more likely to express concerns about rising costs in their health insurance benefit reviews on Glassdoor. For example, mentions of terms like “expensive,” “costly,” or “unaffordable” in health insurance reviews were up 37% between 2023 to 2026.
Growing dissatisfaction with health insurance overlaps with growing dissatisfaction with benefit packages overall as benefits shrink and premiums rise. The average overall benefit rating on Glassdoor fell from 4.24 in 2023 to 4.14 out of 5 stars in 2026. Employee ratings for their health insurance benefits in particular peaked slightly later at 4.22 in 2024, but have declined similarly, falling to 4.11 in 2026. This is on top of further erosion in satisfaction with employees’ total compensation and benefits offerings. So far in 2026, the average compensation and benefit rating on Glassdoor has fallen to 3.68 out of 5 stars, near its lowest level since 2017.
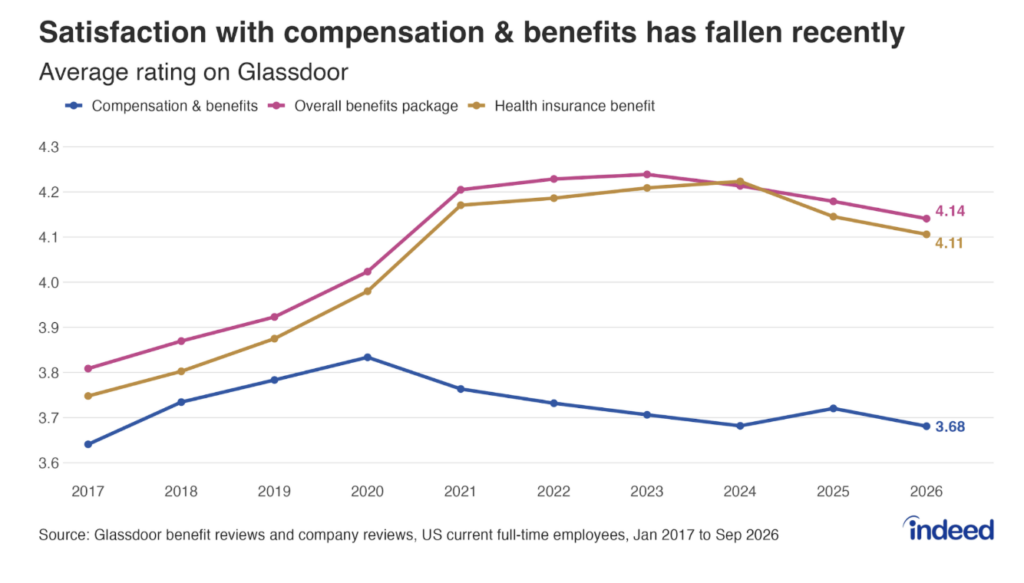
Falling health insurance satisfaction explains about half of the overall decline in benefits ratings since 2023. The surge in complaints about health insurance costs specifically explains about 29% of the decline, highlighting how important health insurance is to workers.
Takeaways for employers and job seekers
Nothing in the 2026 data points to quick relief. Wage growth is positive but cooling, and as long as it trails inflation, real earnings will keep losing ground. Benefit costs have risen every year, especially health insurance, and that is unlikely to reverse any time soon. As those benefit costs climb, more of them tend to land on workers, trimming take-home pay.
For employers, it pays to know that job seekers are paying acute attention to their total pay at this moment. Employers can attract job seekers with a first move that costs almost nothing: advertise what you already offer. Simply naming the benefits employers already provide makes the job more attractive and signals that the employer invests in its people. And while health insurance, paid time off and retirement are the benefits most-valued by workers, other benefits and perks are still valuable. Investing in a wide range of benefits may help an employer stand out to certain workers, particularly younger workers that may expect or value different types of benefits. The bigger risk comes in 2027. A rebound in the labor market could bring more competition for talent, with increased frustration giving way to a wave of turnover – and the compensation and benefits dissatisfaction building is exactly what turns into departures. Employers who let total compensation slide risk losing people to others who don’t.
For job seekers, it pays to understand that total compensation encompasses more than just base pay. Higher health insurance premiums, more restrictive benefit policies and/or outright cuts to benefits programs all reduce workers’ total compensation. As take-home pay is increasingly eaten up by inflation, workers need to be cognizant of everything their employers offer and measure how it compares to other opportunities on the open market. If pay isn’t keeping up, some workers may need a second job to make ends meet, while others may get more out of building in-demand skills that open the door to higher paying roles. Preparing now is worthwhile – and all the more so if labor demand picks up in 2027.
A downloadable version of our full 2027 US Hiring and Worklife trends report can be found here. Detailed methodology statements for this and each of the six chapters in this year’s report can be found here.